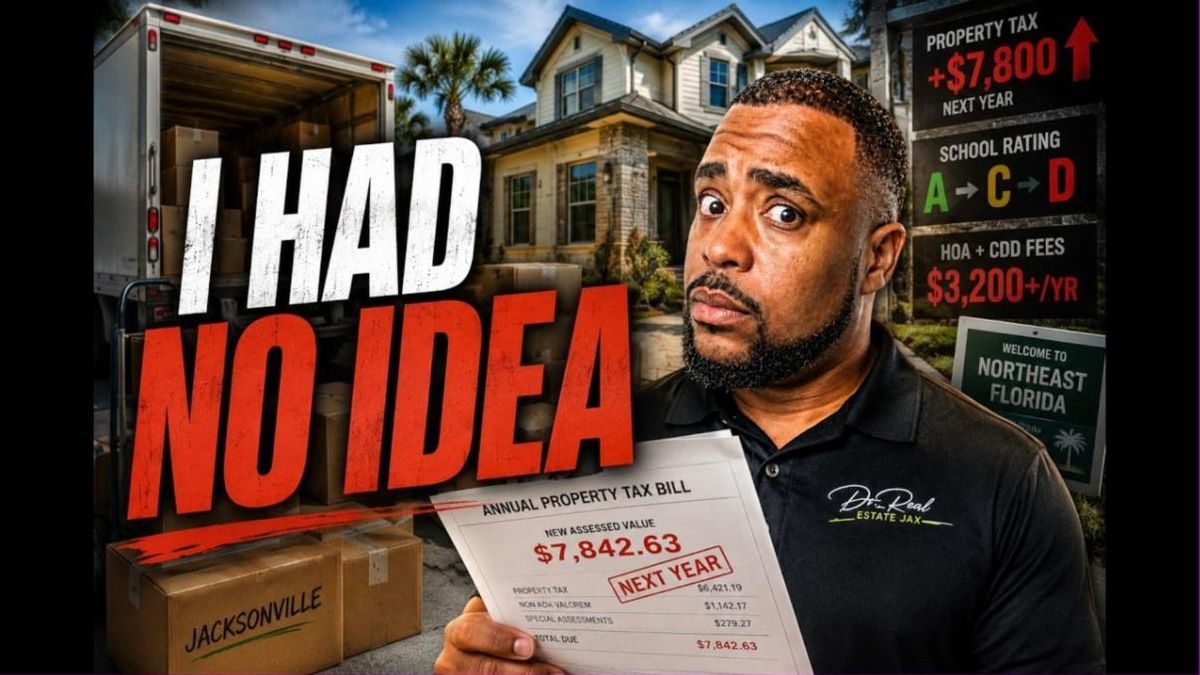
Prefer to watch? The full video is on our YouTube channel: The Truth About New Construction Homes in Jacksonville, FL. The written version is below.
Over the last year, close to 1 out of every 4 homes sold in the Jacksonville area was brand new construction. It's not because everyone fell in love with the smell of fresh paint. It's the interest rate.
A resale home comes with whatever rate the market is charging that day. A new home comes from a builder who can buy that rate down. Same price, two different payments. That's what is pulling buyers toward new construction, and if that's where you're headed, you're not wrong.
But a new build is not a "the price you see is the price you pay" kind of purchase. It's a "the lot costs extra" kind of purchase. A "the refrigerator is sold separately" kind of purchase. Here's everything between the price on your screen and the check you write, and which way of buying new gives you the most leverage.
The short answer: a new construction base price in Jacksonville is a starting point, not the final price. Five things sit on top of it: the homesite premium, structural options, design center upgrades, items not included in the house, and the HOA and CDD. Builders often have more room to negotiate on quick move-in homes, usually through rate buydowns or closing costs rather than a lower price.
Why are builder interest rates lower than bank rates?
When you buy a resale home, your rate comes from the market. According to Freddie Mac, the national average 30-year fixed was 7.28% on October 1, 2026. That's an average, not your quote. A builder doesn't have to hand you the market rate. Many would rather buy your rate down than drop the price, and when we checked builder websites on October 1, more than one was advertising a 30-year fixed around 5.5% on move-in ready homes.
On a $400,000 loan, the gap between 7.28% and 5.5% is about $465 a month in principal and interest. That's a car payment.
Those offers come with conditions. There's usually a deadline, they usually apply only to certain homes (often the ones already built), and they usually require the builder's lender. Some rates are only low for the first year or two. Ask out loud: is this rate fixed for the life of the loan? Then have your own lender put the builder's offer next to theirs.
What does a new construction base price include?
You're scrolling, and there it is: a new community "from the low $500,000s." Then you sit down in the sales center and the number isn't $500,000. Nobody lied. The word "from" was doing a lot of work.
Think of the base price as the menu price. The steak costs what the menu says, but then there's the appetizer, the drink, the dessert, the tax and the tip. The base price is the house with nothing chosen yet: standard flooring, standard homesite, builder standard everything. It's a real house, and almost nobody buys it, because the moment they hand you the option book you start building yours.
Builders say this in writing. ICI Homes' floor plan pages at Seven Pines, for example, note that to-be-built pricing excludes homesite premiums, flex options and design upgrades. Most buyers just don't read it.
What are the hidden costs of new construction in Jacksonville?
Five layers sit between the base price and what you actually pay:
- The homesite premium.
The base assumes a standard lot. The preserve view, the water, the cul-de-sac, the backyard that faces the right way so the sun isn't cooking your lanai at 6 p.m., each one has a number on it. And when a builder has one preserve lot left and four buyers who want it, that's not a negotiation, it's musical chairs. The homesite is also the one thing you can never change later. If there's one place to spend, it's usually the dirt.
- Structural options.
Anything that changes the bones of the house: an extended lanai, a 3-car garage, an upstairs bonus room, a moved wall, an added window. These have a cutoff. Once the slab is poured and framing goes up, the decision is gone. Get the cutoff date in writing before you pick a single finish.
- The design center.
Flooring, countertops, cabinets, lighting, tile, paint. Every selection has a price, and nobody shows you the running total while you order. As a starting point, we tell buyers to plan 8% to 10% of the base price for options, with the lot as its own number on top. Set that budget before you walk in, and never walk into a design studio hungry.
- Everything that isn't part of the house.
The fence. Landscaping beyond the builder package. Blinds for all those tall windows. Gutters, which are almost never included and almost always wanted. And the refrigerator, because the beautiful kitchen often comes with a hole where it goes. None of it is on your builder contract, and all of it tends to land on your credit card in the first 90 days.
- The HOA and CDD.
The HOA (homeowners association) collects dues for common areas and amenities. A CDD (community development district) is how many master-planned communities pay for roads, infrastructure, amenity centers and pools, and its assessment appears on your property tax bill every year. Some communities have one and some don't, so ask up front.
A real example: $517,900 base price vs. $599,060
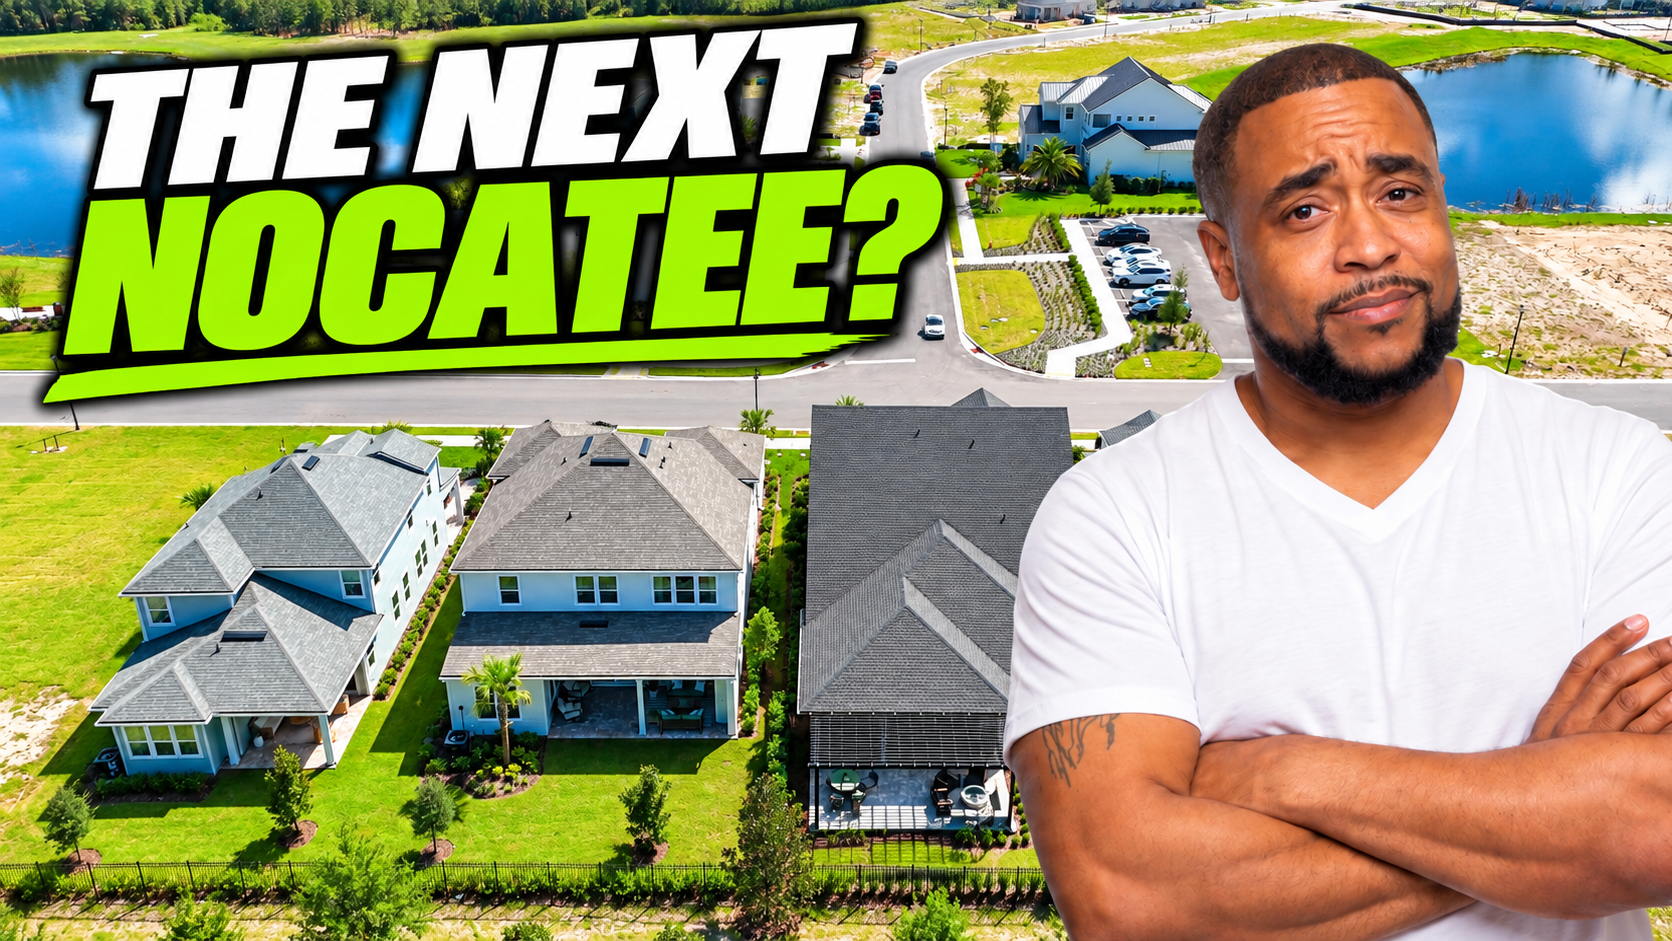
At Seven Pines, ICI Homes has a floor plan called the Nassau. On October 1, its to-be-built base price was $517,900. A Nassau already built on a chosen homesite, with options and design upgrades included, was listed at $599,060. That's about $81,000, or roughly 16%, between the menu price and the check. Same builder, same community, same floor plan.
That's not a markup. The listing says it includes the homesite, the flex options and the design upgrades: layers 1, 2 and 3, each with a dollar sign. And because the builder is holding that finished house, it can be where the deals start. The builder's own site already showed $21,000 off it before anyone made an offer. Numbers like these move often, so check them yourself.
Plan Your Jacksonville Move Around Your Lifestyle
Get help matching the right neighborhood, budget, commute and social lifestyle before you make a move.
Schedule a Consultation
Is it better to buy new construction or an existing home in Jacksonville?
Give the existing home a fair look. You get trees that took decades to grow, streets that are finished, a fence that's up and blinds that are hung. You may be closer to the river, the beach or work. You can see exactly what you're buying before you pay for it. What it asks of you: the roof and the air conditioner have birthdays, and in Florida your insurance company wants those birthdays before it wants your name. Get an inspection and an insurance quote before you fall in love. And it was finished to someone else's taste.
The new build gives you a house no one has lived in, your finishes and layout, a builder warranty, and a roof and air conditioner whose clock starts the day yours does. Many communities come with pools, trails and pickleball, and right now possibly a builder rate. What it asks of you: patience. The oak out front is basically a houseplant. You may be further out than you pictured, there's often a CDD, and the price on the screenshot isn't the price.
Which is better? They're different meals. The question that decides it: do you want to see exactly what you're getting before you pay for it, or choose exactly what you're getting and wait for it?
Should you build from scratch or buy a quick move-in home?
Building from scratch means you pick the homesite, floor plan and finishes, then wait. You get all 5 layers exactly your way. What you give up is leverage. When there's room, it usually shows up as design center money or closing costs, not a lower price.
A quick move-in home (also called an inventory or spec home) is already started or finished, on a homesite the builder chose, with options the builder chose. That Nassau at $599,060 is one. This is where the leverage lives. A drawing costs a builder nothing to keep. A finished house with nobody in it is like a gym membership you're not using. Price, closing costs and those builder rates around 5.5% were all on homes like these.
The catch: someone else did the ordering. So look at the lot first and the kitchen second. If you can wait, build, and spend on what's hard to change: the lot and the structurals. If you're on a timeline, start with the quick move-ins.
Do you need a realtor for new construction?
Here's what a realtor actually does with a builder: we're there to make sure you get everything the builder promises, from the contract to the walkthroughs. What we're not there to do is fight every fee to get you $50,000 off.
Negotiating with a builder is completely different from negotiating on a resale. Some builders will take an offer, and it's usually not the legendary discount everyone brags about. It may be $5,000, $10,000, sometimes $15,000, depending on the builder. A builder can't drop the price drastically on one house, because that lowers the value of every house in the neighborhood, including yours. Many builders also want your agent at the very first visit, so bring us on day one.
5 questions to ask a builder's sales center
- What quick move-in homes do you have right now, and what are you offering on them: price, closing costs, rate, and is that rate fixed for the life of the loan?
- What's the all-in number on this specific homesite with the options I want? Not the base. The all-in.
- Which of these options are structural, and when is my cutoff?
- What's the HOA, is there a CDD, and what will the tax bill look like once the house is on it?
- What's included, and what will I be buying in the first 6 months?
Why the estimated monthly payment online is not your payment
On Zillow and similar sites, there's an estimated monthly payment right under the price. It's very confident, and it has no reason to be. Most of these estimates start with 20% down. Put 5% down and you have a bigger loan and usually mortgage insurance. The rate is an average, not yours, and it doesn't account for builder rates.
Then property tax, which is a big one in Florida. The estimate may lean on what the current owner pays, but a long-time owner's taxable value has been capped for years, and that cap leaves with the seller. The January after you buy, the county resets the value to today. On a brand-new house, the bill on file may only reflect the land. Insurance in the estimate is a placeholder, not a quote, and the CDD often isn't there at all.
We just had a buyer come to us with a payment in mind from one of these sites. When we ran the real down payment, taxes and insurance on that same house, it came out about $400 a month higher. Have your lender build a real payment with every line in it before you fall for a house. For more costs that surprise people after the mortgage, see what to know before moving to Jacksonville.
Our take
The decision isn't new construction or resale. It's which house gives you the life you actually moved here for, at the payment you actually want. If you called us about a new build, we'd start with the quick move-ins and their rate offers, price the all-in number on the homesite you'd really buy, put the builder's financing next to your own lender's, and make sure the HOA and CDD are in the payment before you sign anything.
Sources: Freddie Mac Primary Mortgage Market Survey (October 1, 2026); builder-advertised rates observed on Jacksonville-market builder websites (October 1, 2026, offers carry conditions and deadlines); Zillow new construction report (released September 29, 2026, 12 months ending July 2026); ICI Homes Seven Pines floor plan and inventory pricing (observed October 1, 2026). Payment figures are principal and interest only on a 30-year fixed loan. This is education, not a forecast.
If you're thinking about relocating to Jacksonville or anywhere in Northeast Florida, or you're ready to buy or sell a home, we'd love the opportunity to help.
Our team specializes in making the entire process as smooth and stress-free as possible, whether you're moving from across the country or just across town.
Give us a call, send us a text, or schedule a Zoom consultation, and let's create a game plan that's built around your goals.
Schedule a Meeting
Call or text 904-414-2274
or email info@drrealestatejax.com